Reverse Mortgages
The most flexible financial tool in the industry, designed to help seniors in retirement. Bryan is a Reverse Mortgage Specialist, and he loves answering questions.
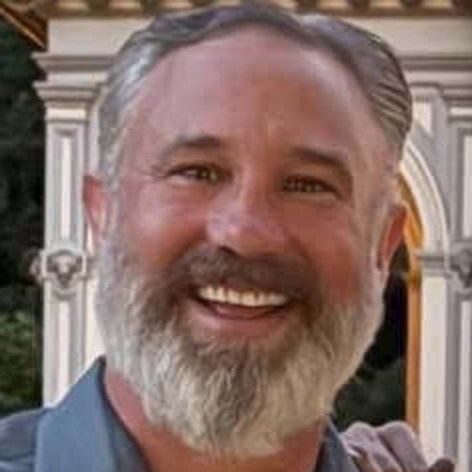
“A reverse mortgage isn’t for everyone, but for those who can benefit from it, it’s life changing.”– Bryan Wild, Branch Manager | Reverse Mortgage SpecialistGet your free estimate
Reverse Mortgage
A reverse mortgage is a wonderful retirement tool. Often it is the last tool needed for a more comfortable retirement.
A reverse mortgage is for anyone who is retired, or about to retire, who doesn’t have the retirement income or assets to retire and accomplish everything on their bucket list. It is a retirement tool designed to help keep seniors in their homes for the rest of their lives, as long as they meet the loan terms.
Today’s reverse mortgages are not the same reverse mortgages you’ve heard about in the past. There have been dramatic changes over the past decade.
A reverse mortgage is the most flexible loan in the industry. It can be used on your current home or to buy a new home. There are fixed-rate options and line of credit options. With either program, you can pay off your current loan, eliminating your monthly mortgage payment. Imagine not having a mortgage payment. Imagine what you could do with that money. How would that affect your monthly budget on a fixed retirement income? Often, this is the final tool needed to help you live comfortably.
Many people over 62 would have enough income to retire if they didn’t have a mortgage payment. Think about it: the money you are spending on a mortgage payment each month could be spent in other areas. Ask yourself how much your quality of life would improve. Peace of mind.
Many retirees could live off their Social Security and pensions if they didn’t have a mortgage payment, even without large savings.
Think about all the goals you would like to accomplish with a reverse mortgage, and give me a call at (925) 788-8949. I would be more than happy to help educate you on how you can accomplish your goals.
What is a HECM?
A reverse mortgage, known as a HECM (Home Equity Conversion Mortgage), is an FHA-insured loan. It allows a senior who lives in the home and qualifies to access a portion of their equity without being required to make a monthly mortgage payment, for as long as they live in the home and keep their property taxes, homeowners insurance and upkeep current.
- Eliminate your mortgage payment
- Create income for a fixed monthly budget
- Tax-free proceeds
- Generally does not affect Social Security or Medicare
- You still own your home
- Government-insured loan (FHA)
- Relaxed qualifying guidelines
Reverse mortgage proceeds are generally tax-free and are not considered income, because they are loan proceeds. However, every financial situation is different. In some cases, money from a reverse mortgage can affect need-based government benefits, not because of income, but because of balances in bank accounts. Sierra Home Mortgage always encourages a consultation with a financial advisor.
Like any homeowner, you still pay property taxes, homeowners insurance, upkeep and any HOA dues.
Watch and learn
More videosSee what a reverse mortgage could do for you
Fill out the short form and Bryan will personally follow up with a free estimate. There’s no cost, no obligation and no credit check.
Prefer to talk now? Call (925) 788-8949.
Adult children and financial advisors are welcome to reach out on a loved one’s or client’s behalf.